

DANA Indonesia Digital Wallet
4.5

My first encounter with DANA Indonesia Digital Wallet makes the most sense in a familiar situation: I want to pay someone or settle a bill without digging through my purse for cash or switching between several financial apps. DANA is a finance app from PT Espay Debit Indonesia Koe, built around keeping everyday cashless payments and transfers in one place. That convenience is its main appeal, though it works best when the people and merchants I need to pay can use the same options.
When a wallet is actually useful
I find a digital wallet most helpful for small, routine tasks rather than as a replacement for every financial service I use. Think of splitting a meal, paying a participating shop, or taking care of a household bill while I’m already on my phone. Keeping those transactions together can make a busy week feel less fragmented, especially if I prefer not to carry cash for every purchase.
There is a practical trade-off: a wallet only simplifies a payment if the recipient or merchant accepts it and I have funds available. I would check which payment methods are commonly used by the people and places I deal with before relying on DANA as my only way to pay. For savings, detailed budgeting, or broader banking needs, I would still use a service designed specifically for those jobs.
Getting Started with DANA
First things first, downloading the DANA Indonesia Digital Wallet is a breeze. Available on both Android and iOS, it’s as simple as heading to your app store, hitting that download button, and you’re off to the races. Once it’s installed, the sign-up process is straightforward. You’ll need to enter some basic info, and voilà, you’re ready to explore.
From setup to the first payment
The useful way to approach a new wallet is to set it up before I’m standing at a checkout. I would complete registration, review the account details, choose a top-up route I’m comfortable with, and make sure I understand how I’ll approve a transaction. That way, the first time I scan a payment code or send money, I’m not trying to learn the interface while someone waits.
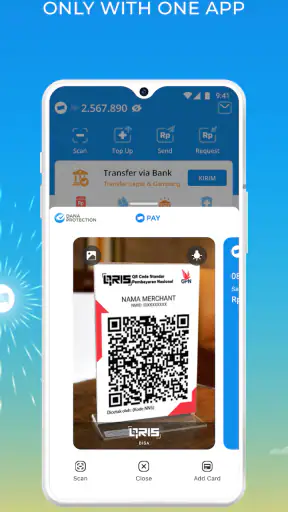
For example, imagine I’m heading out for lunch and a friend has paid the bill. I can check whether they use DANA, add money beforehand if needed, and send my share through the app. If the restaurant accepts QR payments, I can instead scan its code and pay directly. These are different handoffs: one sends funds to a person, while the other completes a merchant purchase, so I’d pause to confirm the recipient or payment destination before approving either.
My practical tip is to treat the first transaction as a small test of the whole route: funding, finding the right recipient or payment option, checking the details, and confirming the result. A wallet can feel quick once that routine is familiar, but a wrong destination is much harder to fix than a moment spent checking the screen.
User Interface and Experience
The first thing that caught my eye was the sleek design. It’s modern, intuitive, and everything is just where you’d expect it to be. Navigating through the app is smooth as butter, which is crucial for any digital wallet. Whether you’re tech-savvy or a newbie, you’ll find it easy to get the hang of things.
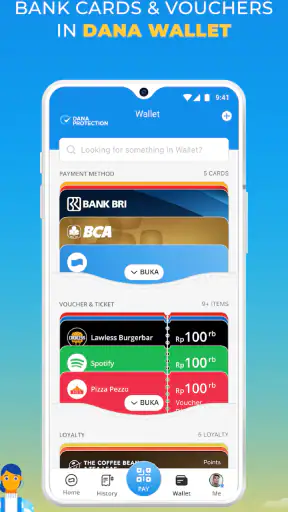
The dashboard is your command center, giving you a quick overview of your balance, recent transactions, and more. This layout helps in quickly spotting what you need without any hassle. It’s clear the developers put a lot of thought into user experience, and it definitely shows.
Features Galore
Now, let’s talk features. DANA is not just about storing money. You can make payments, send money, and even pay your bills right from the app. It’s like having a bank in your pocket, minus the long queues.
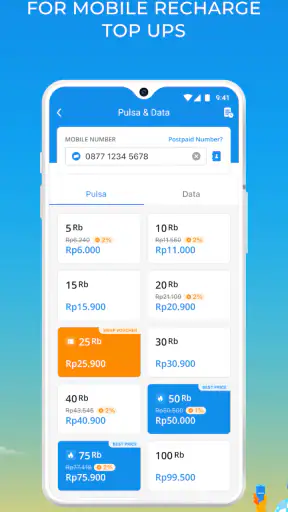
- Bill Payments: Paying bills is a snap. From electricity and water to internet and cable, you can handle it all without leaving your couch.
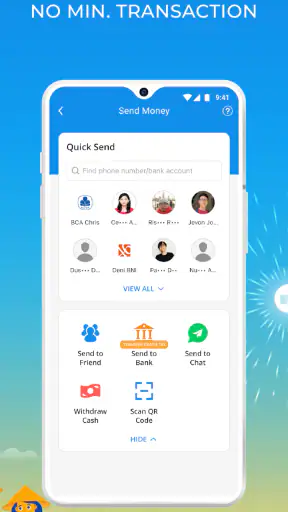
- Transfers: Sending money to friends or family is as easy as pie. You can instantly transfer funds to another DANA user or even to a bank account.
- QR Code Payments: DANA supports QR code payments, making it even simpler to pay at participating merchants. Just scan and pay!
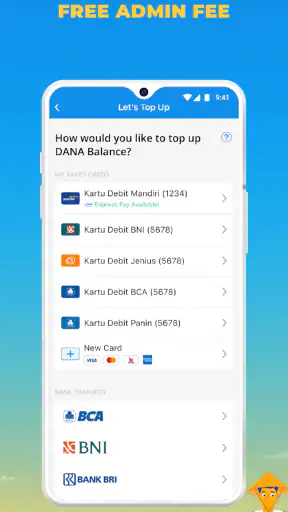
- Top-up Options: Topping up the wallet is flexible with options like bank transfers, credit/debit cards, or even through mini-markets.
Choosing the right handoff
The funding method matters because it shapes how convenient the wallet feels day to day. If I already use a bank account for routine payments, a bank transfer may fit naturally. If I’m topping up while out, a mini-market option may be more useful. I’d pick one reliable method rather than switching between routes without a reason, and keep an eye on the balance before relying on the wallet for a bill due that day.
Transfers also have two distinct audiences. Sending to another DANA user can be a straightforward choice when friends or family already use the app; a bank-account transfer is more suitable when the recipient prefers their existing bank service. I would confirm the recipient information carefully and tell the other person which route I’m using, particularly when a payment is time-sensitive. The most convenient option is the one both sides can actually complete.
For bills, I’d use the app as a task-focused payment step: identify the bill, check the details, approve it, then return to the transaction record to make sure I can see what happened. That last check is a small habit with real value. It helps me distinguish a completed payment from one I still need to follow up on, without assuming that tapping a button alone settles the matter.
Compared with paying in cash, a wallet is easier to carry and can make a digital record of routine spending easier to review. Compared with a bank app, DANA’s appeal is its wallet-centered mix of person-to-person transfers, QR payments, and bills. I would not automatically replace my bank app, though: if I need banking tools beyond those everyday transactions, the bank’s own service may be the better fit. Keeping both is sensible when each has a clear job.
Security Features
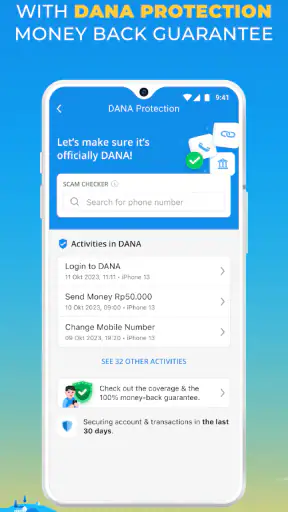
Let’s face it, in the age of digital transactions, security is paramount. DANA doesn’t disappoint. They’ve incorporated multiple layers of security to keep your money safe. Every transaction requires a PIN, and you’ve got the option to enable fingerprint authentication for an added layer of protection. Plus, they send real-time alerts for any activity on your account, so you’re always in the loop.
I’d still treat those protections as part of a careful routine, not a reason to approve a payment on autopilot. I would keep my PIN private, enable fingerprint authentication if it suits the way I secure my phone, and read transaction prompts before confirming. Alerts are most useful when I actually notice them: if something looks unfamiliar, I’d check the transaction history and use the app’s support route rather than ignoring it.
Where the flow can break
The smooth path depends on having a working phone, enough wallet balance, and a recipient or merchant that supports the payment method I’m trying to use. If one part fails, a cash payment or the recipient’s preferred bank service may be a better fallback. That is why I wouldn’t leave home with DANA as my sole payment option for every situation, particularly if I’m heading somewhere where I haven’t checked how people usually pay.
There can also be friction in choosing between a wallet transfer, a bank transfer, and a QR purchase. These are not interchangeable actions, and choosing the wrong path can mean extra steps or a payment that doesn’t reach the intended person. My best safeguard is to slow down at the point where the app asks me to confirm: check who is receiving the money, whether I’m paying a person or a merchant, and whether the amount matches what I intended.
Someone who wants a simple place for everyday transfers, bills, and supported QR purchases is likely to get the most out of DANA. Someone who rarely makes digital payments, prefers handling money only through a bank, or needs a tool for detailed financial planning may find a different option more useful. The app’s strong public uptake—over 100 million installs and an average rating of 4.5 from around 10 million ratings—suggests it has broad appeal, but those figures don’t replace checking whether it fits my own payment habits.
Customer Support
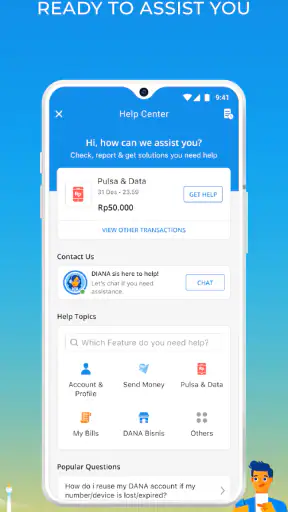
If you ever run into a hiccup, their customer support is ready to help. They offer multiple channels for assistance, including an in-app chat feature. I gave it a whirl, and responses were quick and helpful. It’s reassuring to know there’s someone to help you out when you need it.
If a transfer or bill payment leaves me unsure about its status, I would first look at the transaction history and then contact support through the app if I still need help. Keeping the relevant transaction details nearby makes that conversation more focused. I wouldn’t repeat a payment just because I’m uncertain whether the first attempt went through; checking first can prevent an avoidable duplicate.
DANA is free to download and is rated for everyone. Its current version is 2.128.0, and it supports Android 5.1 and later. Those basics make it accessible to many phone owners, but I’d still check that my own device can run it and that I’m comfortable setting up an account before making it part of a payment routine.
My Final Take
So, what’s the verdict? DANA Indonesia Digital Wallet is a solid choice for anyone looking to simplify their financial transactions. It’s packed with features, easy to use, and secure. Whether you’re paying bills, transferring money, or shopping online, DANA makes it all hassle-free.
It’s like having a tiny financial assistant on your phone, ready to help you manage your money smarter. If you haven’t given it a try yet, I’d say it’s definitely worth checking out. Happy spending, folks!
For me, the strongest reason to keep using it is not that it replaces every other way to pay, but that it can gather several ordinary payment jobs into a familiar mobile routine. I’d start with the task I do most often, learn the funding and confirmation steps, and only then decide whether it deserves a bigger role in my day. If I need wider banking or planning tools, I’d keep those elsewhere; if I want a practical wallet for supported purchases and transfers, DANA is worth considering.
4.5
3.37K Reviews
Pros
- User-friendly interface for easy navigation.
- Quick and secure transactions every time.
- Wide range of payment options available.
- Integration with popular Indonesian services.
- Real-time transaction notifications.
Cons
- Limited international transaction support.
- Occasional app performance issues reported.
- Customer service response can be slow.
- Some features require identity verification.
- Not all merchants accept DANA payments.


